A self-directed IRA can give you more control over retirement savings, including the ability to hold physical gold, silver, and cryptocurrency. But that control comes with strict boundaries.
This IRA prohibited transactions guide explains the IRS rules that can protect your account’s tax advantages – and the mistakes that can put an entire retirement balance at risk.For investors using a Gold IRA or Crypto IRA to preserve purchasing power outside traditional stocks, bonds, and cash, the central rule is straightforward: your IRA is for your retirement benefit, not for your personal use today.
The account must operate as a separate legal and financial entity, administered through the proper custodian and storage or custody arrangement.
What Is an IRA Prohibited Transaction?
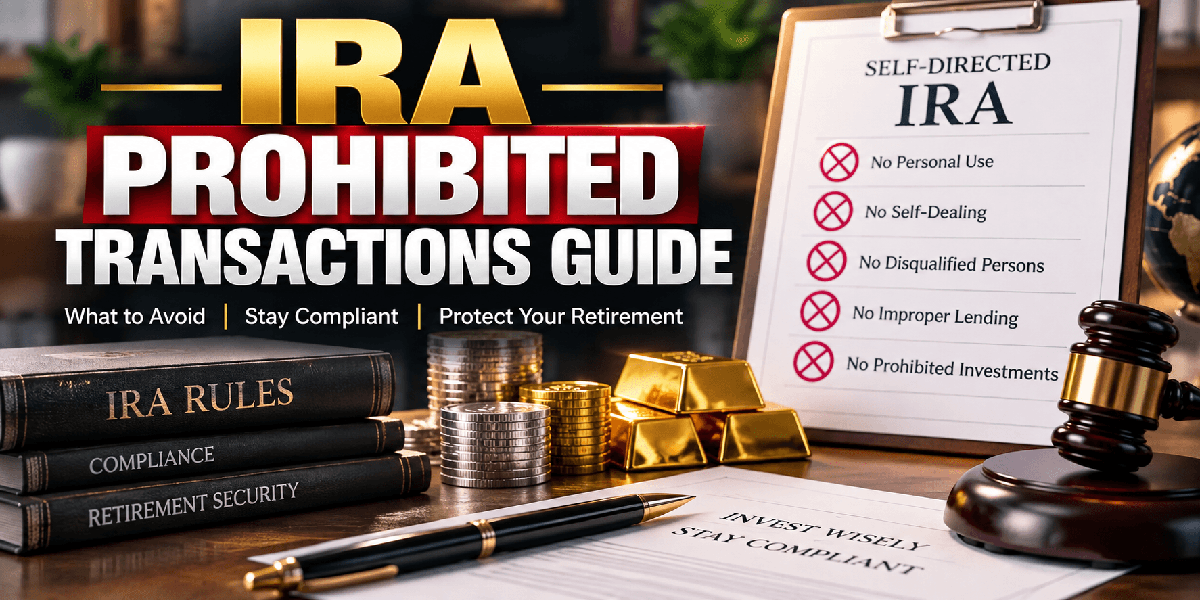
A prohibited transaction is a transaction between an IRA and a “disqualified person” that the Internal Revenue Code does not allow.
The rules are primarily found under Internal Revenue Code Section 4975. They are designed to prevent an account holder from using tax-advantaged retirement assets for personal benefit before retirement.
The concern is not whether a transaction seems reasonable or whether you pay fair market value. A deal can be prohibited even if everyone involved believes it is fair.
What matters is the relationship between the people or entities involved and whether IRA assets are being used in a way the rules prohibit.
The prohibited transaction rules apply to traditional IRAs, Roth IRAs, SEP IRAs, SIMPLE IRAs, and self-directed IRAs.
A Gold IRA is not a separate category of IRA under tax law. It is generally a self-directed IRA that holds IRS-approved precious metals through a qualified custodian.
Who Is a Disqualified Person?
The IRA owner is always a disqualified person. So are the owner’s spouse, parents, grandparents, children, grandchildren, and the spouses of lineal descendants.
Your IRA custodian, investment adviser, and other fiduciaries who exercise authority over the IRA may also be disqualified persons.
Businesses can fall into this category as well. An entity may be disqualified if it is owned 50% or more, directly or indirectly, by the IRA owner, family members described above, or other disqualified persons.
This family definition has limits. Siblings, aunts, uncles, cousins, and most in-laws are not automatically disqualified persons under these rules.
Still, family arrangements deserve extra caution. If an arrangement indirectly benefits you, gives you control over IRA property, or involves a business you substantially own, the details matter.
Related:
- Top 4 Most Secure Gold Depositories for Precious Metals IRA Investors
- Protect Your Metals: Top 10 Bullion Storage Questions to Ask
- How to Buy Silver Bullion Without Costly Mistakes: A Beginner’s Guide
The Transactions the IRS Prohibits
 The law covers several broad categories of transactions. In practical terms, your IRA cannot buy from, sell to, lend to, lease property to, or provide services to a disqualified person.
It also cannot be used as collateral for a personal loan or structured to give you a current personal benefit.
Common prohibited transactions include:
 Selling personally owned gold, silver, real estate, or cryptocurrency to your IRA
- Having your IRA purchase bullion and then storing it in your home, office, safe deposit box, or other location you personally control
- Borrowing money from your IRA or lending IRA money to yourself, a family member, or a company you control
- Using IRA-owned property for personal purposes, such as staying in an IRA-owned vacation home
- Paying yourself, a relative, or a business you control to manage, repair, market, or provide services to an IRA investment
- Using IRA funds to pay expenses that should be personal expenses, or paying IRA expenses with personal funds without understanding the proper account treatment
 Selling personally owned gold, silver, real estate, or cryptocurrency to your IRA
There are also fiduciary rules. A person with authority over the IRA cannot use that authority to benefit personally from an IRA transaction. Nor can they receive an improper fee, commission, or other consideration connected to IRA assets.
Gold IRA Rules: Custody and Storage
 Physical precious metals can be a powerful diversifier when inflation, currency weakness, and market volatility threaten retirement purchasing power.
Yet Gold IRA investors must separate the appeal of physical ownership from the rules governing IRA ownership.
Your IRA can own qualifying gold and silver, but the metals must be held through the IRA’s approved arrangement. In most cases, that means the IRA custodian purchases the bullion and an approved depository stores it.
You may select the metals and direct the investment, but you cannot take personal possession while the bullion remains inside the IRA.
This is why claims about “home storage Gold IRAs” should be approached carefully. Taking IRA-owned coins or bars home can create a serious tax issue, particularly if you have unrestricted access to the metals.
A properly administered Gold IRA uses a qualified custodian and secure depository, with the assets titled to the IRA rather than to you personally.
Not every coin or bar qualifies, either. The IRS generally restricts IRA holdings to certain bullion products meeting purity requirements, along with specific statutory coin exceptions.
Collectible coins are generally not permitted. A reputable precious metals IRA provider can help identify eligible products, but the investor remains responsible for understanding the account structure.
 If you’re searching for the best company, request a FREE Gold IRA Checklist:

Crypto IRA Rules
 The same separation principle applies to cryptocurrency. A Crypto IRA may hold eligible digital assets through a specialized custodian or platform, but the account holder should not treat the wallet as a personal trading account.
Moving IRA-owned crypto to a personal wallet, using it to make purchases, staking it through an arrangement that benefits you outside the IRA, or mixing IRA assets with personal assets can create avoidable compliance questions.
The operational details of crypto custody are still more complex than a standard brokerage account, so clear records, appropriate custody, and an experienced provider are especially valuable.
Investors should also ask how assets are held, who controls private keys, what trading and custody fees apply, and how account reporting is handled.
A lower advertised fee is not always the better value if the platform’s safeguards, support, or tax reporting processes are weak.
For more information, request a FREE Guide to Digital IRAs!
What Happens If You Break the Rules?
The consequences can be severe. When an IRA owner or beneficiary engages in a prohibited transaction, the IRA can lose its tax-advantaged status as of the first day of that tax year.
The entire account may be treated as distributed, not just the asset involved in the transaction.
That could mean ordinary income taxes on the account’s full fair market value. If you are under age 59 1/2, an additional 10% early-distribution tax may apply unless an exception is available.
Depending on the facts, excise taxes and other penalties may also affect disqualified persons involved in the transaction.
Consider an investor with a $350,000 self-directed IRA who stores newly purchased IRA gold at home for convenience. If the arrangement is treated as a prohibited transaction, the potential tax problem is not limited to the value of those coins.
The full IRA balance could be exposed to distribution treatment. That is a high price to pay for control that a professional depository can provide.
Related:
- How to Compare Crypto IRA Providers
- Bitcoin IRAs for Retirement Diversification: Pros, Risks, & Rollover Tips
- BitIRA Review (With Fees): The Best Self-Directed IRA For Cryptocurrency?
How to Keep Your IRA on the Right Side of the Rules
The safest approach is to establish clear separation from the beginning. Use a qualified IRA custodian, fund purchases directly from the IRA, keep invoices and account records, and make sure every asset is titled and stored correctly.
Before any unusual transaction, ask three practical questions:
- Is the other party a disqualified person?
- Does this give me or my family a personal benefit before a lawful distribution?
- Am I using an IRA asset, or my own labor and money, in a way that blurs the line between retirement property and personal property?
Be particularly careful with private investments, real estate, LLC structures, promissory notes, and family businesses.
These investments are not automatically prohibited, but they require more attention than a straightforward purchase of IRA-approved bullion stored at a depository. The more moving parts a transaction has, the more valuable professional review becomes.
A custodian can process paperwork and a dealer can facilitate bullion purchases, but neither role necessarily replaces individualized tax or legal advice.
When a transaction involves family, an entity you own, personal use, compensation, or unusual custody arrangements, speak with a tax professional or attorney who understands self-directed IRA rules before moving funds.
Retirement diversification works best when it is built for the long term. Gold, silver, and crypto can help investors reduce dependence on paper assets and preserve wealth through uncertain periods, but the tax advantages of an IRA are worth protecting with the same discipline.
Unlock the power of gold & silver investing by requesting a FREE Gold IRA Guide: