A Gold IRA can help protect retirement purchasing power from inflation, currency erosion, and stock-market volatility. But gold IRA taxes deserve the same attention as the metals themselves.
The account can offer tax-deferred or potentially tax-free growth, yet one avoidable mistake – an improper rollover, personal possession of IRA metals, or a missed required distribution – can create an unexpected tax bill and penalties.For most investors, the tax treatment is not determined by whether the account holds gold, silver, or other approved bullion. It is determined by the type of IRA, how money enters and leaves the account, and whether the account follows IRS rules for custody and transactions.
This ultimate guide to Gold IRA taxes covers everything you need to know about the tax rules and regulations that can help protect your retirement savings instead of risking penalties.
Let’s begin by taking a look at how Gold IRA taxes work.
How Gold IRA Taxes Work
A Gold IRA is generally a self-directed IRA that holds IRS-approved physical precious metals through a qualified custodian.
Tax rules broadly follow the same framework as conventional IRAs invested in stocks, bonds, mutual funds, or cash.
With a traditional Gold IRA, contributions may be deductible if you meet IRS eligibility rules. Investments inside the account can generally grow tax-deferred.
That means you normally do not owe current tax when the bullion rises in value, when it is sold within the IRA, or when proceeds are reinvested into other approved assets. Taxes are generally due when you take distributions.
A Roth Gold IRA works differently. Contributions are made with after-tax dollars and are not deductible.
In exchange, qualified distributions can be tax-free if the Roth account has met the applicable five-year holding requirement and you are at least age 59 1/2, disabled, or meet another qualifying condition.
That distinction matters to investors who expect higher tax rates in retirement or who want to build a more tax-efficient legacy for heirs.
A traditional account may provide an upfront deduction and tax-deferred compounding, while a Roth can provide certainty about qualified withdrawals later.
Neither choice is automatically best. Your income, expected retirement tax bracket, current deductions, and estate goals all matter.
 Request a FREE Gold & Silver Guide
Gains on Gold Inside the IRA
Outside an IRA, physical gold and certain precious metals may be taxed under collectible rules when sold at a gain.
Inside a properly structured Gold IRA, those annual gains are not taxed as they occur. The IRA wrapper controls the timing and character of taxation.
This can be valuable when gold is serving its intended role as a long-term store of value rather than a short-term trade. It allows the account to rebalance or sell bullion without creating an immediate taxable event.
Still, tax deferral is not tax elimination in a traditional IRA. A later distribution is generally taxed as ordinary income, not at a preferred long-term capital gains rate.
Related:
- How to Start a Gold IRA in 3 Simple Steps
- How to Start a Silver IRA in 3 Simple Steps
- Best Gold IRA Companies for 2026 (Reviewed & Rated)
Tax Rules for Traditional Gold IRA Distributions and RMDs
Traditional Gold IRA withdrawals are generally taxable as ordinary income. Withdrawals taken before age 59 1/2 may also face a 10% additional tax unless an IRS exception applies.
Exceptions can exist for specific circumstances, but they are narrow, so investors should not assume that a market downturn or a desire to hold coins personally qualifies.
Traditional IRA owners generally must begin required minimum distributions, or RMDs, at the age set by current law.
The starting age depends on your birth year, so it is wise to confirm the rule that applies to you before the deadline approaches.
Roth IRAs do not have lifetime RMDs for the original account owner. RMD planning requires special care with physical bullion.
You have two common paths:
 The custodian can sell enough metals to generate cash for the distribution
- Or you can take an in-kind distribution of coins or bars
With an in-kind distribution, the fair market value of the metal on the distribution date is generally included in taxable income for a traditional IRA.
You then own the metal personally, and any future gain or loss is measured from that value. Some retirees prefer taking bullion in kind because they want direct control over their metals.
That can be reasonable, but it does not avoid the tax. It simply changes the form of the distribution from cash to physical gold or silver.
Gold IRA Rollovers and Transfers Without Tax Trouble
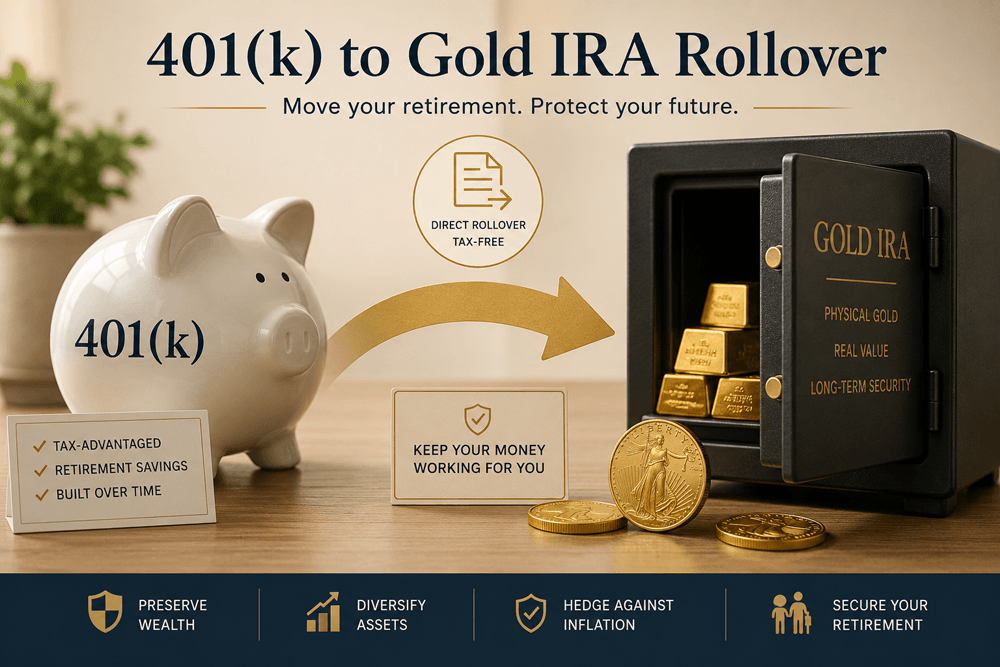
Moving funds into a Gold IRA can often be done without current taxes when handled correctly.
The cleanest route is usually a trustee-to-trustee transfer between IRAs or a direct rollover from an eligible employer plan, such as a former employer’s 401(k) or TSP.
Funds move directly to the receiving custodian rather than passing through your personal bank account.
A 60-day rollover is more complicated. If retirement funds are paid to you, you generally have 60 days to deposit the full eligible amount into another IRA.
Missing that deadline can make the distribution taxable and may trigger the early withdrawal penalty. Employer plans also commonly withhold 20% for federal taxes on an eligible rollover distribution.
To roll over the full balance, you may need to replace the withheld amount from other funds until you receive it back through your tax filing.
There is also a one-rollover-per-12-month rule that applies to certain IRA-to-IRA indirect rollovers. Direct transfers are generally not subject to that restriction.
This is one reason experienced investors usually favor direct transfers and direct rollovers whenever possible.
Do not confuse a rollover with a new annual contribution. Rollovers do not use up your annual IRA contribution limit. New contributions do, and eligibility rules can differ between traditional and Roth accounts.
Prohibited Transactions Can Turn a Gold IRA Taxable
The most serious Gold IRA tax problems often come from prohibited transactions. Your IRA is a separate tax-advantaged account, not a personal metals vault.
The bullion must be held by an approved custodian and stored through an appropriate depository arrangement.
Taking personal possession of IRA-owned gold at home, even with the intention of safeguarding it, can be treated as a distribution.
The IRS also restricts transactions involving disqualified persons, including:
- You
- Your spouse
- Certain family members
- And entities you control
Using IRA assets for personal benefit, lending IRA funds to a disqualified person, or selling your personal coins to your IRA can jeopardize the account.
If a prohibited transaction occurs, the consequences can be severe. The IRA may be treated as distributed as of the first day of that tax year, potentially making the full account value taxable.
Investors under age 59 1/2 could also face the additional 10% tax. The rules are worth respecting because the tax advantage built over years can be lost through one improper act.
Eligible Metals Matter Too
A Gold IRA cannot hold just any collectible coin, jewelry, or family heirloom. The IRS has purity standards and eligibility requirements for precious metals.
Certain widely recognized bullion coins and bars can qualify, while many collectible coins do not.
 Certain widely recognized bullion coins and bars can qualify, while many collectible coins do not.
This is not merely a product-selection issue. Buying ineligible metals with IRA funds can create compliance concerns and make future liquidation more difficult.
A reputable Gold IRA company and custodian should clearly identify which coins and bars are IRA-eligible before a purchase is placed.
What Happens When You Sell Gold in an IRA?
 Selling IRA-owned bullion inside the account does not typically create an immediate tax bill. The proceeds remain within the IRA and can stay in cash, be used to buy other approved metals, or be invested in other assets permitted by the self-directed custodian.
Tax generally enters the picture when money or metals leave the account. This gives investors flexibility to adjust allocations without having every internal sale treated as a taxable event.
It also means fees, spreads, storage costs, and liquidity should be evaluated carefully. Tax deferral does not make an expensive purchase or an unfavorable buyback price a good decision.
For investors using gold as retirement insurance, the disciplined approach is to choose an allocation that supports broader diversification, understand all custodial and storage fees, and avoid treating the account as a short-term speculation vehicle.
Gold can help preserve wealth when paper assets are under pressure, but it should be purchased with clear rules and a long-term plan.
Keep Records and Get Tax Advice
Your custodian will generally issue tax forms for reportable distributions, contributions, conversions, and RMD activity.
Keep records of:
- Rollover paperwork
- Account statements
- Bullion purchase confirmations
- Valuations used for in-kind distributions
- And any correspondence about transfers
Good records make it easier to confirm that a move was completed properly if questions arise later. Tax law changes, and individual circumstances can alter the right approach.
Before converting a traditional IRA to a Roth Gold IRA, taking an in-kind distribution, or moving a large workplace plan balance, speak with a qualified tax professional who understands self-directed retirement accounts.
The goal is not simply to own gold. It is to preserve more of what your retirement savings are designed to protect.
Gold IRA Taxes: FAQ
What are the tax implications of a Traditional Gold IRA?
With a traditional Gold IRA, contributions may be deductible if you meet IRS eligibility rules and investments inside the account can grow tax-deferred; taxes are generally due when you take distributions, and withdrawals are taxed as ordinary income.
How does a Roth Gold IRA differ in taxation from a Traditional Gold IRA?
A Roth Gold IRA uses after-tax dollars for contributions and non-deductible contributions, but qualified distributions can be tax-free if the five-year holding period is met and you are at least 59 1/2 or meet another qualifying condition.
What counts as a prohibited transaction in a Gold IRA and consequences?
Prohibited transactions include taking personal possession of IRA-owned bullion, using IRA assets for personal benefit, or involving disqualified persons; if a prohibited transaction occurs, the IRA may be treated as distributed for the tax year, potentially making the full account value taxable and possibly triggering an early withdrawal tax.
Do I pay taxes on gains inside the Gold IRA when I sell within the account?
No immediate tax is due on gains inside the IRA when you sell within the account; the gains are controlled by the IRA wrapper, and taxes are typically due later when distributions are taken. However, distributions are taxed as ordinary income.
What should I know about rollovers and transfers to a Gold IRA to avoid taxes?
The cleanest route is a trustee-to-trustee transfer or direct rollover from an eligible plan, which avoids current taxes; a 60-day rollover can trigger taxes and penalties if the full amount is not deposited within 60 days, and there is a one-rollover-per-12-month rule for indirect rollovers.
For more information about Gold IRAs, you can visit these related resources:
- Gold IRA Rules: How To Protect Your Retirement With Precious Metals
- Gold IRA FAQ: Everything You Need To Know About Gold IRAs
- Gold IRA Pros And Cons
If you’re searching for the best company, request this FREE Gold IRA Checklist: